
What prequalification usually means
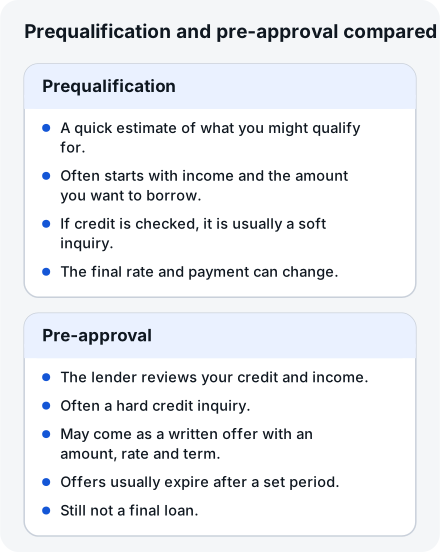
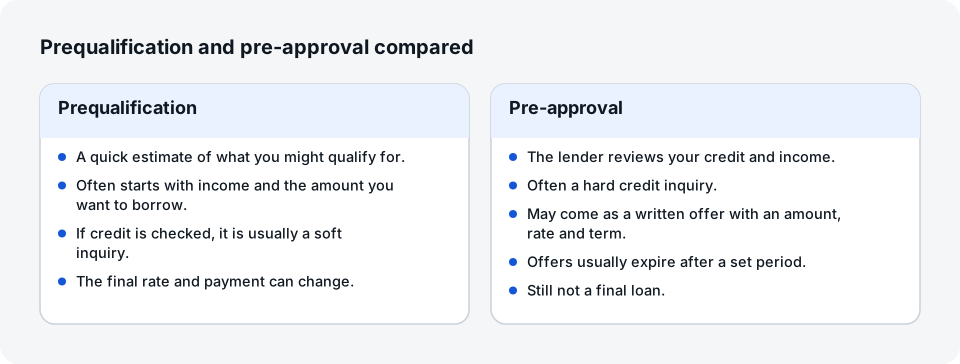
Prequalification is typically a quick estimate of what you might qualify for. It often starts with basic details such as income and the amount you want to borrow. If a lender looks at your credit at this stage, it is usually a soft inquiry, which does not affect your credit score.
Because it is an estimate, the final rate and payment can change when you apply.
What pre-approval usually means
Pre-approval is more involved. The lender reviews your credit and income, often with a hard credit inquiry, and may give you a written offer with an amount, rate and term. These offers usually expire after a set period, commonly a month or two, but each lender sets its own.
A pre-approval is still not a final loan. It can change if the vehicle, the price, the taxes and fees or your finances differ from what the lender reviewed.
Hard and soft credit checks
A soft inquiry does not affect your score. A hard inquiry can lower it slightly for a short time. Many scoring models treat several auto loan inquiries made within a short window as one, but this varies, so ask the lender how it works.
Why the words do not always mean the same thing
Some lenders use both terms interchangeably. Do not assume. Ask each lender directly which check it runs and when.
Questions to ask any lender
- Do you check my credit at this step, and is it a soft or a hard inquiry?
- How long is this offer good for?
- What could change the rate or payment before I sign?
- Is there any fee to apply or to cancel?
How this works when you buy from home
Sending a finance request to a dealership is not the same as applying for a loan. A request shares your contact details and preferences so a person can talk through your options. A credit application, with its credit check, happens only when you choose to submit one, and a good dealer explains what to expect first. Never send a Social Security number by text or email.
. By Tony Tribble, Ballas Chevrolet. General information, not legal or tax advice. Rules vary by state.