
Two ways to finance
The Consumer Financial Protection Bureau (CFPB) suggests getting one or more quotes from a bank, credit union or other lender before you visit a dealer, because it puts you in a better position to bargain. The same advice holds when the dealer is in another state.
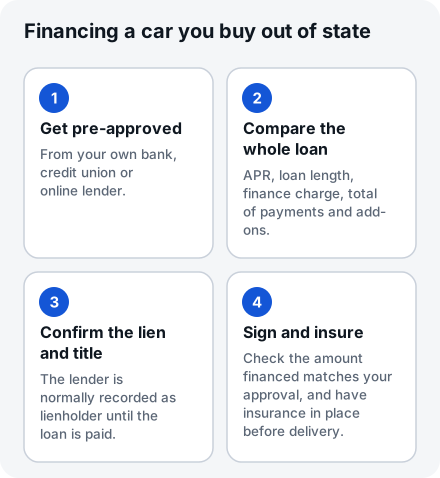
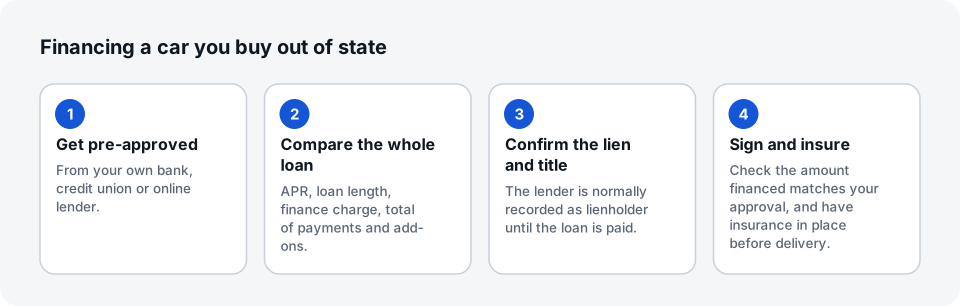
- Pre-approval from your own bank, credit union or online lender. You get the rate, term and other terms before you choose a vehicle, then bring the approval to the dealer.
- Dealer-arranged financing. The dealer sends your application to lenders and presents an offer. Manufacturer promotions, such as special low rates, are usually arranged this way, but only buyers who qualify get them.
Compare the whole loan, not just the payment
Before you sign, a lender must give you written disclosures that show the annual percentage rate (APR), the finance charge, the amount financed and the total of payments. Put the offers side by side and compare those figures.
- APR: the yearly cost of the loan.
- Loan length: a longer loan lowers the payment but usually costs more in total.
- Total of payments and finance charge: what you pay over the life of the loan.
- Add-ons and fees rolled into the amount financed.
- With dealer-arranged financing, whether the rate you were offered is the rate the lender approved or includes an addition by the dealer.
A lender near you, or one the dealer uses
Many buyers use a bank or credit union they already know, which is often in their home state. Ask your lender whether it finances a vehicle bought from an out-of-state dealer, and how it wants the paperwork and the payment sent.
Who holds the title
When you finance, the lender is normally recorded as the lienholder until the loan is paid off. Some states handle this with an electronic lien and title (ELT) system, where the state and the lender exchange records electronically instead of using a paper title. Texas and Nevada, for example, describe ELT programs in which the lender sends an electronic release when the loan is paid and a paper title is then mailed to the owner.
States differ, and not every lender takes part in every state's program. Ask your lender how it records the lien in your state, and ask the dealer how the title paperwork reaches your state's motor vehicle agency.
Paperwork and timing
- Ask when and how documents will be signed, in person, by mail or electronically.
- Check that the amount financed on the purchase agreement matches your lender's approval.
- Have insurance in place before delivery. Lenders typically ask for proof of it.
- Ask when you will receive the registration paperwork and what your state needs from you.
Questions to ask
- Will my lender finance a vehicle from a dealer in another state?
- Can you beat my pre-approval, and what are the APR, term and total of payments?
- How will the lien be recorded in my state, and who sends the title paperwork?
- Which fees and add-ons are included in the amount financed?
. By Tony Tribble, Ballas Chevrolet. General information, not legal or tax advice. Rules vary by state.